
FloatMe: Fast Cash Advance App
- Rating
- 4.5
- Downloads
- 1.00M
- Content Rating
- Everyone
FloatMe: Fast Cash Advance App - Screenshots
Pros
- Quick application process with a simple
- user-friendly interface.
- May help cover small
- unexpected expenses before payday.
- No traditional credit check may make access easier for some users.
- Clear repayment dates help users understand when advances are due.
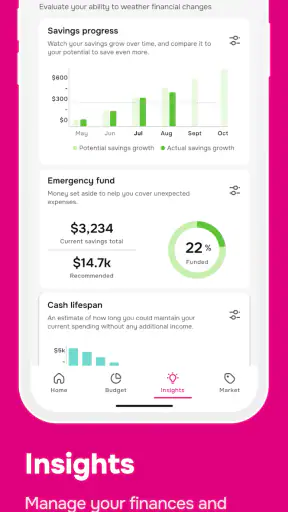
- Optional financial tools can help track spending and manage cash flow.
Cons
- Membership fees may apply even if you do not frequently use advances.
- Advance limits can be low for larger emergency expenses.
- Eligibility and available amounts may change based on account activity.
- Repayment may be withdrawn automatically
- affecting your next paycheck.
- Availability and features vary by state and supported banking providers.
FloatMe: Fast Cash Advance App - Description
- App Name
- FloatMe: Fast Cash Advance App
- Package Name
- io.floatme.floatmeapp
- Developer
- FloatMe
- Category
- Finance
- Last Updated
- Oct 4, 2018
- Version
- 8.21.0
If you are looking at FloatMe because payday is still a few days away, the most important thing to understand is its role: this is a finance app built around requesting a cash advance rather than managing a full bank account or replacing a long-term budget. I found that distinction helpful from the start. It keeps the app focused on a short-term problem, but it also means you should treat it as a temporary option, not as extra income.
FloatMe is free to install, developed by FloatMe, and available to everyone. It has become a well-known choice in its niche, with an average rating of 4.5 from around 78 thousand ratings and more than 1 million installs. Those figures suggest that many people find the basic idea useful, although popularity should not be confused with a guarantee that every request will work for every user.
What to expect before you begin
The app’s central promise is straightforward: it can help eligible users seek money before payday without an interest charge or a traditional credit check. In practical terms, I would approach it as a bridge for a specific, necessary expense, such as groceries, transportation, or a bill that cannot reasonably wait. I would not use it to fund shopping, entertainment, or a recurring gap in my monthly budget.
The first thing a new user should expect is an eligibility process. A cash advance app needs enough information to assess whether it can make an offer, so installation alone does not mean money will immediately appear. The app guides you through its own checks, and the result depends on your situation and the details you submit. That is normal for this type of service, but it is worth knowing before you plan around a particular amount.
I also recommend reading every screen carefully instead of tapping through setup as quickly as possible. The useful question is not simply “Can I get cash?” but “What exactly will I receive, when will it arrive, and what will I need to do afterward?” A calm reading of the terms is especially important when you are already stressed about a deadline.
FloatMe is not the same as a credit card, a personal loan, or a budgeting tool. A credit card may offer a reusable line but can create interest charges if you carry a balance. A conventional loan may provide more money but usually involves a longer application and repayment structure. A budgeting app can help you avoid the emergency altogether, but it cannot solve today’s shortfall. FloatMe sits between those choices, aimed at a smaller and more immediate need.
That position is its main strength and its main limitation. If you need a modest bridge and expect your next paycheck to restore your balance, the focused design makes sense. If your income is irregular, your expenses consistently exceed your pay, or you need a large amount, I would look at a broader financial solution instead.
Setting up an account without rushing
After installing the app, I would begin with the account details and identity information it requests, keeping my personal and banking information accurate. A mismatch between what I enter and what can be verified may slow the process or prevent an advance, so guessing is a poor shortcut. Having the relevant account and income details ready makes the first session less frustrating.
The app is free, but that does not mean every financial action connected with an advance should be assumed to have no conditions. I would inspect the offer and any delivery choices shown in the app before accepting anything. The phrase “no interest” is useful, but it should not replace reading the complete explanation of the transaction.
One practical tip is to set up FloatMe before an emergency rather than during one. Installing it while standing in a checkout line leaves little time to resolve a verification problem or understand the available choices. A quiet setup on an ordinary day lets you learn where the request flow begins and what information you may need later.
Another useful habit is to keep your expected repayment date realistic. If the app asks you to confirm timing, do not choose a date based on wishful thinking. A short-term advance only helps when the repayment fits your next income cycle. Taking money today while knowing that the next paycheck is already committed can turn a small problem into a repeating one.
The current version is 8.21.0, and the app runs on Android 7.0 or later. That makes it accessible to people using older Android phones, although I would still keep the operating system and the app updated when possible. Updates can affect the layout, verification steps, or the way your device handles security, so screenshots from an older version may not match what you see.
Getting to the first useful result
The first meaningful success is not merely opening the home screen; it is completing a request that you understand and can repay. I would start by reviewing the amount available to me, then compare it with the exact expense I am trying to cover. Asking for only what is necessary is a better discipline than treating the available amount as a spending target.
For example, imagine that a paycheck is due soon but a necessary grocery trip cannot wait. I would calculate the smallest amount that covers the food, submit the request, and keep the repayment date visible in my personal budget. I would also avoid using the advance for several unrelated purchases. That separation makes it easier to see whether the app solved one temporary problem or simply postponed a larger one.
The request flow is easier to manage when you have a clear purpose. Before tapping the final confirmation, I would ask myself three questions: Is this expense essential? Will my next income cover the repayment without skipping another bill? Have I read the delivery and repayment details shown in the app? If any answer is uncertain, I would pause rather than accept money just because it is available.
FloatMe’s no-interest positioning can make the decision feel less serious than borrowing usually does. In my view, that is exactly why users need their own guardrails. “No interest” does not make an advance free of responsibility, and it does not remove the risk of depending on advances repeatedly. The app can reduce the cost of a short bridge, but it cannot repair an income-and-expense mismatch by itself.
I would also save a simple note outside the app with the amount requested, the reason for it, and the expected repayment date. That small step is surprisingly useful when several bills are due at once. It prevents the advance from blending into ordinary spending and gives you a quick way to check whether the transaction helped your plan.
Where first-time users can get confused
The biggest possible misunderstanding is assuming that an application automatically leads to an advance. Eligibility is part of the experience, and the amount or timing available to one person may not be the same for another. I would avoid making a nonrefundable purchase based on money that has not actually been approved and delivered.
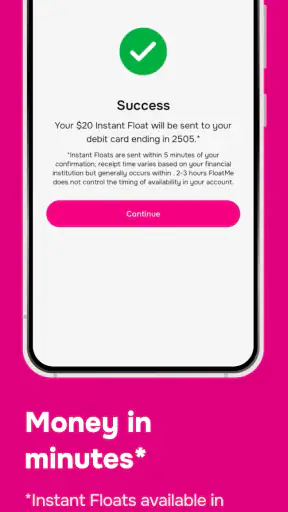
Another point that deserves attention is delivery timing. An advance intended for an urgent bill is only useful if it reaches you in a timeframe that matches the deadline. Review the delivery option presented during the request rather than relying on a general expectation. If the expense is due immediately, confirm that the selected route fits the situation before accepting.
Users may also confuse the app’s free installation with a promise that every related service or transaction is costless. I would read the complete offer each time, including any wording about how funds are delivered and how repayment works. Financial apps deserve the same careful reading as a contract, even when the interface looks simple.
The absence of a traditional credit check can be appealing, particularly for someone who is worried about a credit score. Still, it does not mean the app ignores financial information altogether. The service needs to evaluate requests in its own way, so accurate account details and a consistent financial picture remain important. I would not enter information that is incomplete simply to move faster.
There is also a behavioral trap: using a cash advance to pay for a previous cash advance. If that is becoming your pattern, the problem is no longer a one-off timing issue. At that point, a conversation with a bank, credit counselor, employer, or trusted adviser may be more useful than another short-term request. FloatMe is better suited to an occasional gap than to permanent dependence.
Who will benefit most from this approach
I think the app is most suitable for a person with predictable income, a clearly defined short-term expense, and enough room in the next pay cycle to repay the advance. That user can make a measured request, solve the immediate issue, and return to normal spending without needing a new advance immediately afterward.
It can also be useful for someone who wants an alternative to overdrawing a bank account or placing a small essential purchase on a high-cost credit product. The advantage is not that borrowing becomes harmless; it is that a focused advance may be more appropriate than using a much larger financial product for a small gap.
I would be more cautious if your income changes from week to week, your bank balance is already committed to rent and utilities, or you regularly reach payday with nothing left. In those cases, even a no-interest advance can create pressure at the next pay period. A budgeting system, a payment arrangement with the biller, or a longer-term debt solution may fit better.
FloatMe is also not the right choice if you want detailed expense categorization, investment tools, savings automation, or a complete view of your financial life. Its purpose is narrower. Choosing it for those tasks would be like using a flashlight as a general lighting system: it may do one job well, but it is not designed for everything around it.
How it compares with familiar alternatives
Compared with an overdraft, a cash advance app can feel more deliberate because you request the money for a defined need instead of allowing a transaction to push your account below zero. The better option depends on the costs and terms attached to each choice. I would compare the actual consequences, not just the convenience of tapping a button.
Compared with a credit card, FloatMe may be easier to understand for a one-time shortfall because it is not presented as an open-ended spending line. A credit card is more flexible for planned purchases and can be useful when paid in full, but it can also encourage a balance that lasts beyond the original emergency. FloatMe’s narrower purpose can be a useful boundary for someone who wants to avoid that kind of revolving debt.
Compared with a personal loan, the app is aimed at a smaller and faster problem rather than a major expense. A personal loan may be more appropriate for consolidating debt or covering a substantial, planned cost, while using a short-term advance for that purpose would likely be a poor fit. I would never choose a small emergency tool to handle a financial obligation that needs months of structured repayment.
Compared with borrowing from a friend or family member, the app offers a more private, app-based route, but personal borrowing may be more flexible in timing and repayment if both sides agree clearly. The right choice depends on your relationships, urgency, and ability to repay. Privacy and convenience are valuable, but they should not distract from the repayment obligation.
Small habits that make the experience safer
My first recommendation is to use a separate mental category for the advance: “already spent.” Once the money arrives, do not count it as part of your normal balance. Assign it immediately to the expense that justified the request. This prevents the common mistake of seeing the advance as spare cash and then discovering that the original bill still needs attention.
Second, check your upcoming automatic payments before accepting an advance. A subscription, utility withdrawal, or scheduled transfer can consume the balance you intended to use for repayment. Even if FloatMe’s own process is clear, your wider account activity may not be. A quick review of the next several transactions can reveal a problem before it becomes urgent.
Third, keep the app as a backup rather than checking it whenever your balance feels uncomfortable. Frequent checking can normalize borrowing for ordinary spending. I would open it with a specific question and a specific amount in mind, then close it once that decision is complete.
Finally, if the request does not work, do not immediately submit repeated applications with altered information. Recheck what you entered, make sure your account details are current, and consider whether the expense can be delayed or handled another way. A failed request is frustrating, but rushing into multiple financial applications rarely improves the underlying situation.
My recommendation for a first-time user
After reviewing the app’s purpose and workflow, I see FloatMe as a practical emergency bridge for a narrow situation: you need a modest amount before payday, you understand the request and repayment terms, and your next income can absorb the repayment. The free app, accessible age rating, and focus on advances make it approachable, while the lack of a traditional credit check may matter to users who want to avoid that route.
At the same time, I would not describe it as a complete answer to financial stress. Its value depends heavily on timing, eligibility, and disciplined use. The safest first step is to install it before you are under pressure, complete setup carefully, and learn the request flow without assuming that approval is guaranteed. When a real need appears, ask only for the amount tied to that need and record how it will be repaid.
My honest conclusion is that FloatMe works best when it remains occasional and intentional. It is a reasonable alternative to using a larger credit product for a small, temporary gap, but it should not become part of your normal monthly income. If you can use it as a short bridge and return to your regular budget, it may be genuinely helpful. If every payday requires another bridge, the next step should be a broader plan rather than another advance.
FAQ
What is FloatMe: Fast Cash Advance App, and how does it work?
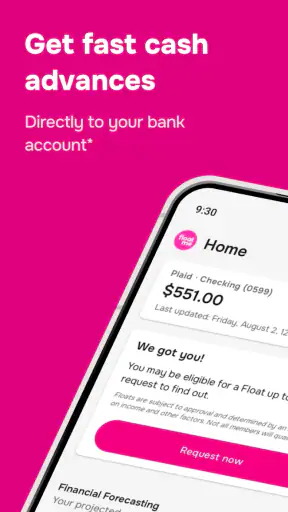
FloatMe is a financial app designed to help eligible users access a small cash advance before their next payday. After connecting a supported bank account, the app reviews account activity and displays whether an advance may be available. If approved, users can request funds through the app and repay the advance according to the displayed terms. Availability, limits, and eligibility can vary by user.
How much money can I borrow with FloatMe?
The amount available through FloatMe depends on several factors, including your account history, income patterns, recurring deposits, and repayment behavior. The app generally focuses on relatively small advances rather than large personal loans, so it may be more suitable for covering a short-term gap than financing a major expense. Always review the amount, delivery timing, membership charges, and any optional fees before confirming a request.
Does FloatMe charge fees or require a subscription?
FloatMe may use a membership-based model, meaning access to certain features can involve a recurring subscription charge. Additional costs may apply depending on how quickly you want funds delivered or which services you use. Because pricing and terms can change, carefully check the fee summary shown in the app and read the current membership agreement before signing up. Canceling a request does not necessarily cancel a subscription.
How quickly does FloatMe deposit the cash advance?
The delivery time depends on the option selected, your bank, account verification, and whether the request is approved during processing hours. Standard transfers may take longer, while faster delivery options could involve an additional charge. FloatMe should not be treated as a guaranteed instant solution, especially if your account information needs verification or if a bank transfer is delayed. Confirm the estimated arrival time before submitting your request.
Is FloatMe safe to use, and what information does it require?
FloatMe typically requires personal and financial information, including identity details and a connection to a supported bank account, so it can verify eligibility and assess repayment ability. As with any financial app, download it only from an official app store, review its privacy policy, and use a secure password. Avoid sharing login credentials outside the official connection process, and remember that approval is not guaranteed.


